Protecting Homes: Why insurance matters
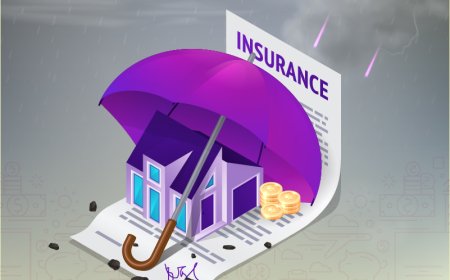
Floods, fires and burglaries can cause major losses; home insurance offers financial protection
Property Pulse
A home is among the most valuable assets a person owns. Families spend years saving to build a house or purchase an apartment, often investing additional lakhs in interiors, furniture and appliances. Yet many homeowners do not give insurance the same importance as health or motor insurance.
Heavy rains, floods, cyclones, fires, electrical short circuits and water leakages can cause considerable damage to residential properties. Home insurance offers financial protection against several such risks, helping owners meet repair, reconstruction or replacement expenses. However, understanding what a policy covers, its exclusions and the appropriate sum insured is essential before purchasing one.
Structure and contents: Two different covers
Home insurance generally provides two types of protection. Structure insurance covers the physical building, including walls, roofs, floors, doors, windows, permanent electrical wiring and sanitary fittings. Depending on the policy, compound walls, garages, water tanks and permanently installed solar panels may also be covered.
Jewellery, paintings and other valuables may require additional coverage.
What risks are covered?
Depending on the policy, protection may include damage caused by accidental fires and explosions, floods and inundation, cyclones, storms, earthquakes, landslides and specified water leakages.
How much insurance does your home need?
A common mistake is calculating the insurance requirement based on the property's market value. Building insurance should generally be based on reconstruction cost, excluding the land value.
Can tenants also buy insurance?
Yes. Tenants can purchase contents insurance to protect their furniture, appliances and personal belongings. The landlord generally insures the building structure, while tenants protect their own possessions. These covers serve different purposes.
Buyers check
- A lower premium should not be the only deciding factor.
- Check separate coverage for the structure and contents.
- Verify protection against floods, earthquakes and cyclones.
- Examine burglary cover and limits on jewellery and valuables.
- Understand deductibles, sub-limits and exclusions.
- Preserve purchase bills, photographs and other claim-related documents.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0