Can you get a home loan without buying a house?
A home loan can be used for more than buying a ready property. Depending on the lender, borrowers may access finance for home construction, renovation or eligible extensions.
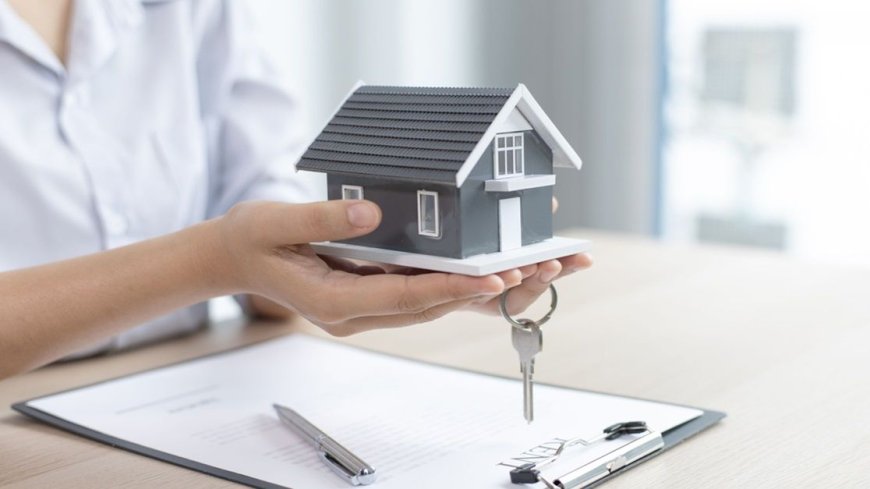
Housing finance can also fund construction, renovation and eligible extensions
Property Pulse
A home loan is not limited to buying a completed house or apartment. Depending on the lender and the property, housing finance can also be used for constructing a home on an owned plot, renovating an existing house or carrying out an eligible extension.
For example, a person who owns a 200-square-yard plot and plans to spend ₹50 lakh on construction may be eligible for construction finance subject to the lender’s assessment, approved plan and other conditions.
Eligibility depends on income, age, employment or business stability, existing loans, credit history and the value and legal status of the property. A credit score around 750 or above may be viewed positively by many lenders, but it does not guarantee approval.
A ₹40-lakh loan, for example, can have a very different total interest burden depending on whether it is repaid over a shorter or longer tenure.
The key point is that a home loan is housing-purpose finance, not unrestricted cash. Construction, renovation and eligible extensions can qualify, but the purpose, property and documentation must satisfy the lender’s rules.
LOAN OPTIONS
• Construction loans can fund homes on eligible owned plots.
• Loan disbursement may be linked to construction stages.
• Renovation and eligible extensions can qualify.
• Income, credit history and existing EMIs affect eligibility.
• Check processing, legal, technical and prepayment charges.
• Verify title, EC, plans and required approvals.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0