Buying Property Above ₹50 lakh: Deduct 1% TDS from Amount Payable
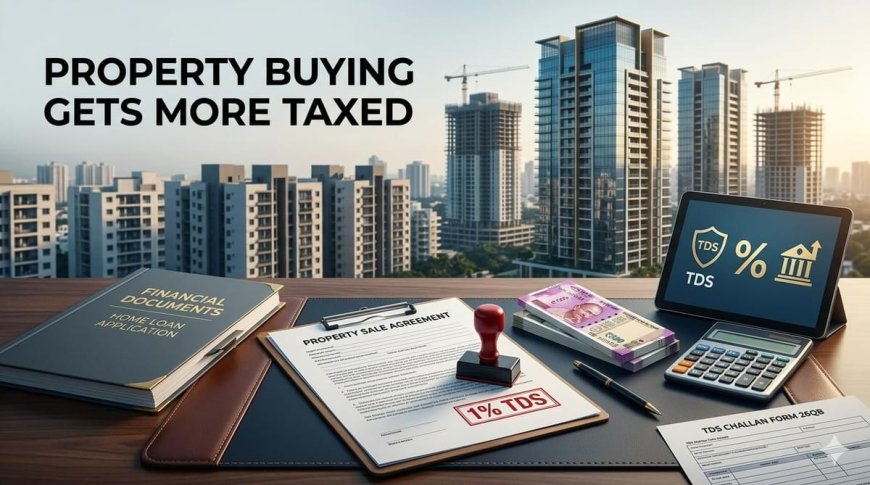
Property buyers purchasing immovable property worth ₹50 lakh or more must comply with the 1% TDS requirement, calculated on the sale consideration or stamp duty value, whichever is higher.
PROPERTY PULSE
Buying an immovable property worth ₹50 lakh or more involves tax compliance obligations that buyers must account for alongside registration and stamp duty payments. Tax Deducted at Source (TDS) is an important requirement in such transactions, and failure to deduct, deposit or report the tax correctly can result in interest, late fees and penalties.
Under the applicable provisions, buyers are generally required to deduct TDS at 1 per cent when purchasing immovable property for ₹50 lakh or more. The threshold is assessed with reference to the consideration or stamp duty value, whichever is higher. The responsibility for deducting and depositing the tax rests with the buyer.
The buyer must deduct the applicable TDS from the amount payable to the seller and deposit it with the government within the prescribed deadline. The buyer must also complete the required reporting and provide the seller with the relevant TDS certificate.
The requirement applies to qualifying transactions involving land, buildings or both, subject to the conditions prescribed under the income tax law.
Also Read: Homebuyers Opt Functional Layouts, Make Convenience Their Priority
Buyers must verify the seller's PAN details before proceeding with the transaction. Where the seller fails to furnish a valid PAN, a higher rate of TDS may apply under the applicable provisions.
Buyers should verify the seller's PAN status well before making payments. The seller's residential status also matters, as purchases from non-resident sellers are governed by separate provisions.
Failure to deduct or deposit TDS within the prescribed period can result in interest and other consequences. For qualifying property transactions covered by the Income-tax Act, 2025, the deducted amount must be deposited along with Form 141 within 30 days from the end of the month in which the deduction is made.
Form 141 replaces Form 26QB for reporting TDS on purchases of immovable property from resident sellers from April 1, 2026.
Many property buyers focus primarily on registration and stamp duty payments while overlooking the TDS process. However, deducting the applicable tax, depositing it with the government and filing the relevant statement are equally important responsibilities.
Buyers should maintain payment records, challan receipts and TDS certificates to establish compliance. The applicable procedure depends on the seller's residential status and the transaction date.
Buyers should understand their obligations before making payments and seek assistance from a Chartered Accountant or tax professional where necessary.
Tax Compliance:
- 1% TDS applies at ₹50 lakh
- Deposit and file within 30 days
- Stamp duty value also affects threshold
- Buyer responsible for deducting tax
- Invalid PAN may trigger higher deductions
- Form 141 replaces Form 26QB
Also Read: Focus on First-Time Buyers, Say Experts
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0